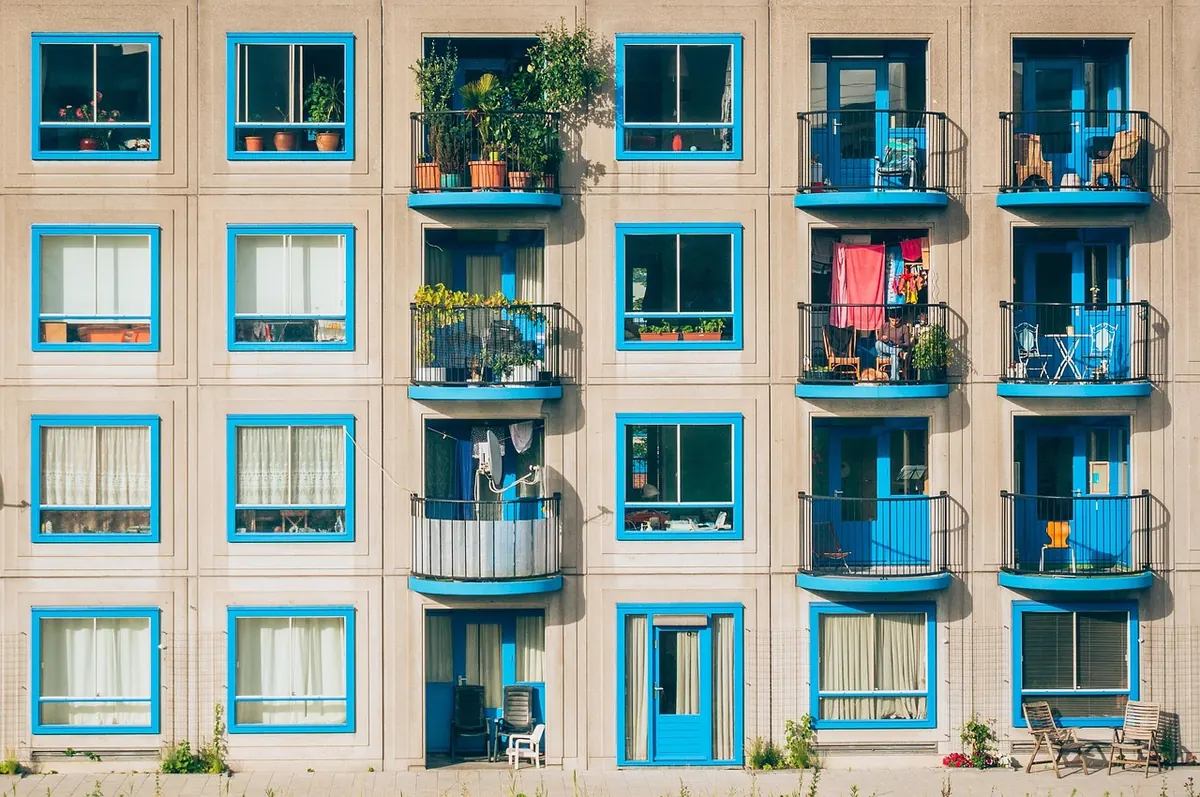
Buying your first flat is mostly a paperwork exercise punctuated by a few large emotional spikes. The viewing takes twenty minutes; everything around it takes weeks. If you are looking at flats in Mercia Quarter — a conversion in one of the old canal-side buildings, a modern block near the tram stop, or the upper floors of a Victorian terrace — the fifteen steps below are the ones that decide whether the purchase runs smoothly. Work through them in order, keep everything in one folder, and don't skip the dull parts. The dull parts are where the money is.
Steps 1–4: Sort the money before you fall for a flat
Before you stand in a hallway imagining your sofa, get the practical side stable. Nothing sours a purchase faster than finding a funding gap three weeks before completion. A small example: on a £180,000 flat with a 10% deposit, you might have £18,000 saved, but the total cash needed on day one could be closer to £22,000 once legal fees, survey, mortgage fee, searches, and removals are added. That gap is the difference between a calm completion and a frantic call to family.
- Build the whole pot, not just the deposit. The deposit is the headline figure, but add legal fees, survey, mortgage arrangement fee, searches, removals, and a month of rent overlap if you are leaving a rental. If some of the money sits in a Lifetime ISA or a Help to Buy ISA, check the withdrawal rules with the provider well in advance rather than the week you need it. Withdraw too early and you can lose the bonus; withdraw too late and you can miss the completion deadline.
- Get an agreement in principle. It is usually free, valid for a few months, and it tells an agent you are credible. A broker who can see the whole market may find a better deal than one bank's adviser; either way, take regulated mortgage advice before you commit to anything. Keep the paperwork as a PDF and name it clearly, because you will be asked for it more than once.
- Look at your credit file early. Three months ahead is comfortable. Register on the electoral roll at your current address, tidy up anything small and unresolved, and don't take out new finance for furniture you haven't chosen yet. A mobile phone contract or a car loan taken out during the purchase can change how a lender views your affordability.
- Ask for the ongoing costs in writing. Service charge, ground rent, council tax band, reserve fund, planned works. A flat with a low service charge and a roof that needs replacing is not a cheap flat. Ask for the last three years of service charge accounts and the current budget, not just a verbal summary.
Steps 5–7: Viewings and making the offer
Two viewings beat one. Go at a busy time of day, then again in the evening, when you can hear the neighbours, the road, and whatever the bin store sounds like at seven o'clock. In Mercia Quarter, that second viewing matters even more: a canal-side flat can be peaceful on a Tuesday morning and lively on a Friday night, and a modern block near the tram stop can be convenient but not silent.
Questions to ask while you are standing in the kitchen
- How many years are left on the lease? Below eighty, extending it gets more expensive, so factor that in.
- What is the ground rent, and how is it reviewed? Watch for clauses that double it every ten or fifteen years.
- What has the service charge been for the last three years, and exactly what does it cover?
- Is there a healthy reserve fund, and are major works planned or already out for consultation?
- Who manages the building, and how responsive are they? Ask for the managing agent's name and check online reviews if you can.
- What is the parking situation, and is it allocated, permit-only, or first-come-first-served?
- Are there any known issues with damp, ventilation, or noise from neighbouring units or the road?
Once you have those answers, you are ready to move from looking to acting. The next three steps are where most first-time buyers either gain or lose leverage.
- Step 5: Do the second viewing properly. Take photos, measure rooms, test the water pressure, open the windows, and visit at a different time of day. If the flat is in a conversion, listen for neighbours through the walls and check the communal hallways for signs of neglect.
- Step 6: Make your offer in writing, subject to survey and contract. State your position clearly: first-time buyer, mortgage agreed in principle, solicitor ready, flexible on completion. A clean offer with fewer conditions is often worth more to a seller than a slightly higher one that might fall through.
- Step 7: Prove your funds and instruct your solicitor. Once the offer is accepted, the agent will ask for ID, proof of deposit, and your mortgage agreement in principle. Instruct a solicitor who has done leasehold flats before, and ask for a fixed fee or a clear estimate. Do not use the seller's solicitor, even if it seems convenient.
Steps 8–11: The legal middle
This is the part that feels slow and then suddenly very fast. Your solicitor will handle the searches, raise enquiries, and review the lease. Your lender will arrange a valuation, which is not the same as a survey. Keep chasing politely but regularly; a purchase that goes quiet for two weeks often needs a nudge.
- Step 8: Review the lease and management pack. Check the lease length, ground rent, service charge, buildings insurance, and any restrictions on pets, subletting, or renovations. If the lease is short or the terms are unusual, ask your solicitor to explain the cost and process of extending or varying it.
- Step 9: Commission a survey. A homebuyer report or full building survey can reveal problems the valuation will not. In an older conversion, look for roof, damp, and structural issues. In a modern block, ask about cladding, fire safety, and any remediation plans that could affect your mortgage or service charge.
- Step 10: Wait for searches and enquiries. Local authority searches, water and drainage, environmental, and sometimes coal mining or flood searches. In a canal-side location, flood risk and drainage can be relevant. Your solicitor will raise enquiries with the seller's solicitor and the management company.
- Step 11: Confirm your mortgage offer. Once the valuation is done and the lender is satisfied, you will receive a formal mortgage offer. Read it carefully: check the term, rate, fees, and any conditions. Return signed documents promptly and keep a copy.
Steps 12–15: Exchange, completion and keys
The final stretch is about dates, money, and insurance. Once contracts are exchanged, the purchase is legally binding, so you need to be certain about the completion date and your funds.
- Step 12: Agree the completion date and review the contract. Your solicitor will send you the contract and transfer deed. Read them, ask questions, and make sure the date works with your rental notice period and removals.
- Step 13: Exchange contracts. You will pay a deposit, usually 10%, and the completion date is set. From this point, you cannot change your mind without losing money. Make sure your buildings insurance is in place from exchange, not completion, unless the freeholder covers
Photo: Jakub Zerdzicki / Pexels